))
))
))
))
))
))
))
))


The type of construction contract determines far more than how a contractor gets paid.
In fact, it defines who carries the design risk, who carries the cost risk, how the parties manage changes, how they certify progress and, ultimately, how exposed the contractor is to cost overruns.
This becomes particularly important in large EPC, Lump Sum, Turnkey, BOT and PPP projects, where the client’s commercial structure may not contain enough detail to manage the actual cost of construction.
In short, the key principle is simple:
The level at which a contractor is paid is not necessarily the level at which a contractor must control its costs.
For enterprise contractors, the contractual Bill of Quantities (BoQ) is therefore only one dimension of project control.
As a result, true construction cost control requires connecting the BoQ, Work Breakdown Structure (WBS), Cost Codes and actual site execution.
And this is where a construction-specific ERP becomes critical.
First, FIDIC, EPC, Lump Sum, BOT and PPP Are Not the Same Thing
People often use these terms together. However, they describe different aspects of project delivery.
- FIDIC provides standardized forms of construction and engineering contracts.
- EPC — Engineering, Procurement and Construction describes a delivery model. Here, the contractor assumes responsibility for engineering, procurement and construction.
- Lump Sum (LS) primarily describes a pricing arrangement. In this case, the contractor agrees to deliver a defined scope for an agreed price, subject to the contract’s provisions for variations and other adjustments.
- BOT — Build-Operate-Transfer combines construction with a concession period during which the private party operates the asset before transferring it.
- PPP — Public-Private Partnership is broader still. It typically involves a long-term contractual relationship between the public and private sectors. This relationship covers combinations of design, construction, financing, operation and maintenance.
In practice, these structures can overlap.
For example, a contractor can deliver an EPC project as a Lump Sum Turnkey contract using the FIDIC Silver Book.
From a cost-control perspective, however, what matters is the amount of commercial, design, construction and performance risk transferred to the contractor.
The greater the risk, the greater the need for internal cost granularity.
FIDIC Red, Yellow and Silver: Different Allocations of Risk
Under the FIDIC Red Book, the Employer traditionally provides most of the design, while the contractor executes the construction works.
As a result, this generally creates a relatively direct relationship between design, quantities, measurement, progress and payment.
- The FIDIC Yellow Book shifts more design responsibility toward the contractor. Consequently, the contractor must increasingly manage engineering, procurement, construction, time and cost as interconnected processes.
- The FIDIC Silver Book, commonly associated with EPC/Turnkey delivery, then transfers substantially greater responsibility to the contractor.
In other words, the Employer is effectively purchasing an outcome:
Deliver the required facility, plant or infrastructure asset according to the agreed requirements, price and completion obligations.
For the contractor, however, delivering that outcome may involve tens of thousands of activities, resources, purchase orders, material movements, labor transactions, machinery hours and subcontractor operations.
That creates a major cost-control problem.
The EPC Paradox: A Simple Commercial Price Can Hide Enormous Construction Complexity
For example, consider a simplified EPC BoQ containing a line such as:
Structural Works — $12 million
From the client’s commercial perspective, that may be perfectly adequate.
From the contractor’s cost-control perspective, however, it is almost meaningless.
In practice, that $12 million could contain:
excavation, dewatering, reinforcement, concrete, formwork, structural steel, labor, cranes, pumps, temporary works, consumables, logistics, material wastage, specialist subcontractors and indirect resources.
The original BoQ may not provide this level of engineering analysis. Even so, the contractor cannot simply accept the lack of detail.
Instead, the contractor has to manufacture that granularity internally.
This is why Cost Codes become strategically important.
Cost Codes Can Become the First-Level Rough-Cut Budget
ProjectVIEW ERP approaches construction cost control through three interconnected project dimensions:
BoQ ↔ WBS ↔ Cost Codes
- The BoQ represents the commercial dimension: what the client is buying and what the contractor is ultimately selling.
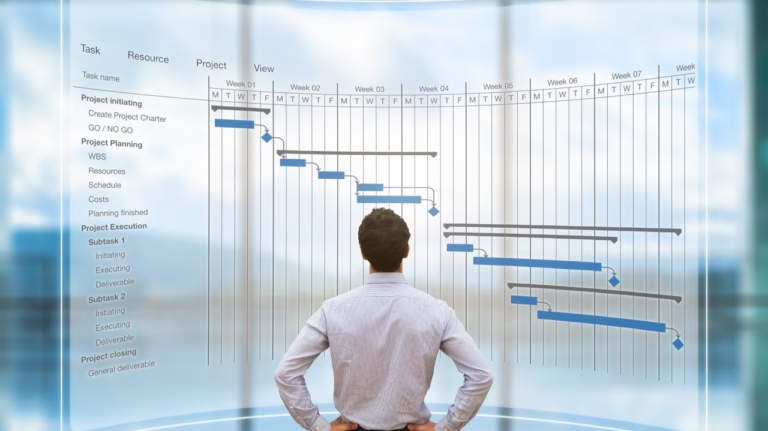
- The WBS, by contrast, represents the execution and time dimension: where, when and in what sequence the team must perform the work.
- Finally, the Cost Code (Cost Control Accounts) represents the internal cost-control dimension: how the contractor classifies and monitors expenditure.
In addition, ProjectVIEW supports assigning Cost Codes to the BoQ budget and establishing relationships between the BoQ budget and project scheduling structures.
When the EPC BoQ lacks sufficient engineering detail, Cost Codes can therefore provide the first internal rough-cut decomposition of the project budget.
For instance, the contractor can internally distribute a high-level BoQ item such as Structural Works across cost categories for earthworks, concrete, reinforcement, formwork, structural steel, labor, machinery and subcontractors.
As a result, the contractor no longer depends on the client’s commercial structure to decide how to control the project internally.
The WBS Adds the Dimension the BoQ Does Not Have: Time
First, Cost Codes answer:
What type of cost are we incurring?
Then, the WBS answers:
Where and when are we performing the work?
ProjectVIEW’s tendering and budgeting methodology also lets the team associate resources, productivity assumptions and timeframes with BoQ structures and project planning.
This creates three different but interconnected views of the same project:
BoQ = Commercial
WBS = Time and execution
Cost Codes = Cost classification
Together, these three connected dimensions establish the project’s initial cost-control framework.
But the real intelligence begins when construction starts.
Site Execution Creates the Missing Engineering Detail
After all, a budget is an assumption.
Construction is reality.
Every day, the construction site generates information that can progressively enrich the original budget.
How much work did the site complete?
How many labor hours were required?
And how much material did the crews consume?
Similarly, how many hours did a crane, excavator or other piece of equipment work?
How much subcontracted work did the project execute and certify?
What should that amount of physical progress have cost?
And what did it actually cost?
ProjectVIEW’s cost-control methodology captures daily transactions, including project progress, employee transactions and machinery transactions. It then uses them to build the actual project cost picture.
In addition, its wider construction-management model connects materials, subcontractor certifications, labor productivity and machinery utilization with BoQ–WBS–Cost Code relationships.
This is how a relatively rough EPC budget starts becoming a detailed engineering cost model.
From Rough-Cut Budget to Child-Level Cost Analysis
At tender stage, the contractor may begin with:
BoQ → Cost Code
Then, during project planning, this becomes:
BoQ → Cost Code → WBS
Finally, during construction it develops further:
BoQ → Cost Code → WBS → Resources → Daily Transactions
In this way, the original high-level budget progressively acquires child-level operational detail.
As a result, management can eventually analyze a structural works budget down to a specific WBS activity, cost category, crew, material consumption, machinery utilization, subcontractor certificate and physical progress transaction.
Instead of simply knowing that structural works are over budget, management can begin asking:
Which activity?
Which Cost Code?
Which resource?
Which crew?
Which subcontractor?
Which material?
Which machine?
Which day?
That is a fundamentally different level of cost control.
Daily Work Orders: The Surgical Dissection of Construction Cost
However, contractors do not actually build projects through monthly financial reports.
Instead, they build them through daily work.
The ultimate level of construction cost control is therefore the ability to associate operational transactions with the project’s commercial, scheduling and cost structures.
A daily work transaction should answer:
What are we building? — BoQ
Where are we building it? — WBS
What category of expenditure does it involve? — Cost Code
Who performed the work? — Labor or subcontractor
Which materials did they consume? — Materials
What equipment was required? — Machinery
How much progress did they achieve? — Physical progress
What should that progress have cost? — Budget
What did it actually cost? — Actual Cost
This is what we mean by the surgical dissection of a construction project.
ProjectVIEW also extends the same logic into procurement. Users can associate materials procurement and warehouse processes with BoQs, WBS and Cost Codes. This allows expenditure to remain connected with its project purpose from requisition through purchasing and site consumption.
Subcontractor contracts and certifications can also carry Cost Codes, bringing subcontracted work into the same cost-control structure.
The BoQ Should Become a Living Cost Structure
Therefore, the BoQ received during tendering should not remain a static Excel document disconnected from execution.
ProjectVIEW can import an Excel BoQ and transform it into a hierarchical structure of BoQ code lines. Estimators can then associate materials, labor, plant and subcontractors with those lines.
Once construction starts, reality begins enriching the original model.
The digital evolution becomes:
Tender BoQ
→ Cost-Coded Budget
→ WBS-Linked Project Baseline
→ Resource Budget
→ Daily Site Transactions
→ Actual vs Budgeted Cost
→ Productivity and Resource Variances
→ Management Action
This closes one of construction’s most persistent information gaps:
the gap between estimating what construction should cost and understanding what construction is actually costing.
Why This Matters Even More in EPC and Lump Sum Projects
Moreover, the financial consequences become particularly significant under EPC and Lump Sum contracts.
For example, imagine a contractor has:
Contract revenue: $500 million
Budgeted cost: $450 million
Expected margin: $50 million
Suppose execution ultimately costs $485 million. The additional $35 million does not disappear because the client’s BoQ lacked sufficient detail.
Instead, it comes directly from the contractor’s margin.
The objective of construction cost control therefore cannot simply be to report the overrun afterward.
The objective must be to identify deviations while management still has time to intervene.
In practice, that means continuously comparing:
Budgeted vs actual labor productivity
Budgeted vs actual material consumption
Planned vs actual machinery utilization
Budgeted vs certified subcontractor costs
Planned vs actual physical progress
Budgeted vs actual project cost
ProjectVIEW’s cost-control model captures site transactions. It then compares execution against the project baseline rather than waiting for accounting to become the first indication that something has gone wrong.
From Traditional Cost Reporting to “Quantum” Cost Control
Traditional financial ERP is very good at answering:
What did we spend?
Construction cost engineering, however, needs to go considerably further:
What did we spend, where did we spend it, what resource consumed it, what physical progress did it produce, what should that progress have cost, why is there a deviation and what can we still do about it?
By connecting:
BoQ ↔ WBS ↔ Cost Codes
and continuously feeding that structure with:
Labor ↔ Materials ↔ Machinery ↔ Subcontractors ↔ Progress
ProjectVIEW ERP progressively breaks project performance into smaller measurable units.
This creates what we call “quantum” Cost Control: the continuous decomposition of project cost and performance into increasingly granular operational elements. This lets managers identify deviations closer to where and when they originate.
Instead of discovering at month-end that concrete works are over budget, management should be able to drill toward the underlying operational cause.
That is the difference between reporting a cost overrun and controlling one.
The Real Digital Thread: From Tendering to Construction
Many enterprise contractors still operate through disconnected technology layers.
One system handles estimation.
Primavera handles scheduling.
Meanwhile, another platform manages site activities.
Procurement operates through corporate ERP.
Subcontractor information sits elsewhere.
Accounting records financial transactions.
Finally, Excel attempts to reconcile everything.
The result is not digital transformation.
It is digital fragmentation.
By contrast, ProjectVIEW ERP takes a different approach by creating an integrated construction-specific backbone connecting:
Tendering → Budgeting → Planning → Procurement → Site Execution → Subcontractors → Cost Control
First, the client’s BoQ becomes the commercial starting point.
Cost Codes provide the contractor’s internal cost structure.
Next, the WBS adds schedule and execution.
Procurement consumes the budget.
Meanwhile, site transactions record reality.
Subcontractor certifications record external production.
Progress then measures what the site actually built.
And the resulting information continuously feeds project cost control.
DANAOS designed the ProjectVIEW architecture specifically to connect estimation, procurement, subcontractors, site operations and cost control around the common dimensions of BoQ, WBS and Cost Codes.
The objective is not another dashboard.
It is a digital cost-control backbone for construction.
In EPC, the Contract Price Is Only the Beginning
FIDIC, EPC, Lump Sum, BOT and PPP arrangements allocate responsibilities and risks differently.
But one principle becomes increasingly important as more risk moves toward the contractor:
Commercial simplicity must never be confused with operational simplicity.
An EPC contractor may receive a relatively high-level contractual BoQ.
Still, that does not make granular cost control impossible.
Instead, it makes granular cost control more important.
ProjectVIEW ERP addresses this by using Cost Codes as first-level rough-cut budgeting elements, connecting them with contractual BoQ items and time-based WBS activities, and then progressively enriching this structure with real construction data:
Labor productivity.
Materials exploitation.
Machinery utilization.
Procurement.
Subcontractor certifications.
Physical progress.
Daily site transactions.
As a result, the project can progressively evolve from:
Contract → BoQ → Cost Code → WBS → Resources → Daily Execution → Actual Cost
And this is where a construction-specific ERP becomes fundamentally different from a generic financial ERP.
Accounting tells you where the money went.
Construction cost engineering must tell you why it went there—and early enough to do something about it.
In the end, for EPC and Lump Sum contractors carrying significant execution risk, that difference can ultimately determine whether they protect their project margin or explain why it disappeared.